Tax season in the UAE isn’t scary anymore, it’s just new. Since Federal Decree-Law No. 47 of 2022 came into force, every business owner has had to get comfortable with corporation tax services, vat registration Dubai, and the paperwork that ties both to a working corporate bank account Dubai. If the acronyms feel overwhelming, you’re not alone, and that’s exactly why so many founders bring in a vat registration consultant before their first filing deadline. Here’s the full picture, without the jargon.
The 9% Question Everyone’s Asking
The headline number is simple: 0% on the first AED 375,000 of taxable income, 9% on everything above it. Qualifying Free Zone Persons can still access 0% on qualifying income, but the moment income falls outside that category, standard rates kick in.
What trips people up isn’t the rate. It’s the registration deadline. Businesses must register within 9 months from the end of their financial year, or 3 months from incorporation, whichever comes first. Miss it, and the FTA hits you with a flat AED 10,000 penalty, no reminder, no grace period.
| Situation | What Applies |
| Taxable income under AED 375,000 | 0% rate, registration and filing still required |
| Taxable income above AED 375,000 | 9% rate on the excess |
| Qualifying Free Zone Person | 0% on qualifying income, 9% on non-qualifying income |
| Late registration | AED 10,000 flat penalty |
| Late payment | 14% per annum, uncapped |
Why Even a Dormant Company Can’t Skip This
A dormant business holding a live trade license is generally still a Taxable Person and must file a nil return unless formally deregistered. This catches out a lot of founders who assumed “no income, no filing.” Working with corporation tax services early means someone is tracking these obligations before the FTA sends a notice instead of a reminder.
VAT Registration Dubai: A Different Track Entirely
Here’s where confusion creeps in. Corporate tax and VAT run on separate tracks with separate registrations, even though the same authority, the FTA, oversees both.
- Mandatory VAT registration: taxable turnover exceeds AED 375,000 in the past 12 months, or is expected to within 30 days.
- Voluntary VAT registration: taxable turnover or expenses exceed AED 187,500, giving early-stage businesses the option to register ahead of time.
- Zero-rated supplies (exports, certain healthcare and food items) still count toward your threshold, even though no VAT is charged on them.
VAT registration Dubai applications require trade license details, authorized signatory information, and corporate bank account details, which is exactly why the account needs to exist before you start the application, not during it.
Where the Corporate Bank Account Fits In
A corporate bank account Dubai isn’t just a nice-to-have. It’s the operational backbone behind almost every compliance step above.
- WPS salary processing requires an active account through a CBUAE-approved bank.
- Corporate tax filings and payments must run through a registered corporate account.
- VAT-registered businesses use corporate banking details for FTA filings.
- Government and private-sector clients often expect payment routed through a verified corporate account, not a personal one.
Without this piece in place first, both your tax filings and your VAT registration Dubai application stall before they start.
Getting the Sequence Right
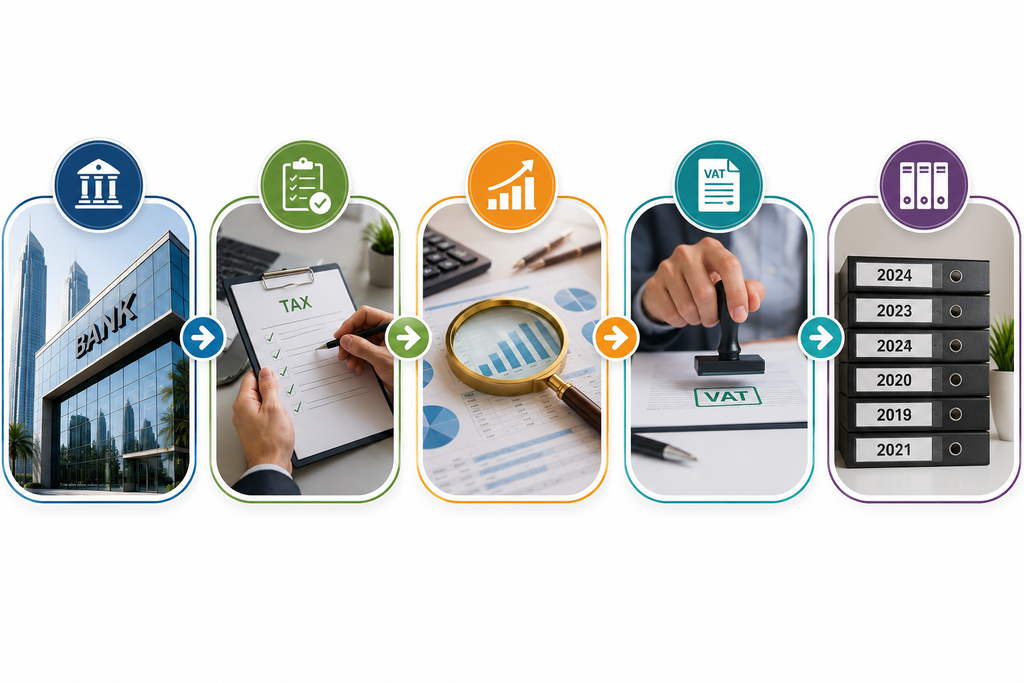
A vat registration consultant typically walks clients through this order, because doing it out of sequence creates rework:
- Open the corporate bank account Dubai requires before any tax registration.
- Register for corporate tax within the applicable deadline.
- Track taxable turnover against the AED 375,000 VAT threshold.
- Register for VAT once mandatory, or earlier if voluntary registration makes sense.
- Set up bookkeeping that supports both filings, since the FTA keeps records for seven years.
When to Bring in Professional Help
Founders juggling formation, banking, and two separate tax tracks often underestimate how quickly deadlines overlap. Corporation tax services exist precisely for this overlap, handling registration timing, filing calculations, and the audited financial statements now required for taxable persons with revenue exceeding AED 50 million.
Ready to get your corporate tax, VAT, and banking sorted without the guesswork? OnTime Business connects you with the right corporation tax services and vat registration consultant support so nothing slips past a deadline.
Also Read : How Can Corporation Tax Services Help Businesses Stay Compliant?
Frequently Asked Questions
1. What’s the current corporate tax rate in the UAE?
0% on taxable income up to AED 375,000, and 9% on income above that threshold.
2. Do I need a corporate bank account Dubai has approved before registering for VAT?
Yes. VAT registration applications require corporate banking details, so the account should be set up first.
3. Is corporate tax registration mandatory even at 0% income?
Yes. Every Taxable Person must register and file, regardless of whether tax is actually owed.
4. What’s the VAT registration threshold in Dubai?
Mandatory at AED 375,000 in taxable turnover over 12 months; voluntary from AED 187,500.
5. What happens if I miss the corporate tax registration deadline?
A flat AED 10,000 penalty applies automatically, with no reminder or grace period.
6. Does a dormant company still need to file?
Generally yes, a nil return is required unless the company has formally deregistered with the FTA.
7. Can a vat registration consultant handle both VAT and corporate tax?
Many consultants manage both tracks together, since the FTA governs both under one portal, Emara Tax.
8. How long must financial records be kept for tax purposes?
Seven years from the end of the relevant tax period, per FTA requirements.
9. What’s the penalty for late corporate tax payment?
Late payment of Corporate Tax may result in administrative penalties calculated in accordance with the UAE Tax Procedures and Corporate Tax penalty rules.
10. Are free zone companies exempt from corporate tax compliance?
No. Free zone businesses may qualify for 0% on qualifying income but still must register and file.
Also Read : VAT Registration Dubai: New 5-Year Deadline Rule Every Business Must Know